DBF are a class act. We used them for the sale of a house. Professional, clear and responsive. Craig and Belinda who handled our case were great. Nothing was too much trouble, responsive and easy to get hold of.
Dave Weston

Our Manchester office is rated 5 stars on Google

Categories
The Chancellor’s recent Budget has introduced significant changes affecting inheritance tax (IHT) and how Wills should be structured.
Whilst the chancellor has frozen the inheritance tax ‘IHT’ thresholds until 2030 – £325,000.00 nil rate band ‘NRB’ with a further main residence band ‘RNRB’ available £175,000.00 – only if your assets are less than £2million and you have children. She has introduced other IHT revenue streams which will impact many more estates.
From April 2027, private pension pots will be included in the value of an individual’s estate when calculating their IHT liability. This could significantly increase the IHT charge on estates, especially for those with large pension pots- rather than impact on distribution of your estate through your Will.
If you own a business or agricultural property, changes effective from April 2026 will impact how these assets are passed on in your Will.
The changes mean that IHT will be paid when the assets are more than £1 million per person, but this is in addition to the existing nil rate bands and exemptions. Over that sum, IHT will be payable at a 50% rate i.e. a tax rate of 20%. But 100% tax relief is available up to £1 million.
Trusts settled after the budget will share the personal allowance of £1million – this stops a potential tax saving plan.
The real worry to many is that estates previously qualifying for RNRB may no longer qualify if the pension pot, is added into the equation.
Should you die over the age of 75 not only will the unused pension pot face IHT if over the threshold but the beneficiaries will pay income tax on the income drawn from it.
It is wise and recommended to seek independent financial advice from a pension expert, especially as the government has yet to refine the details of the legislation.
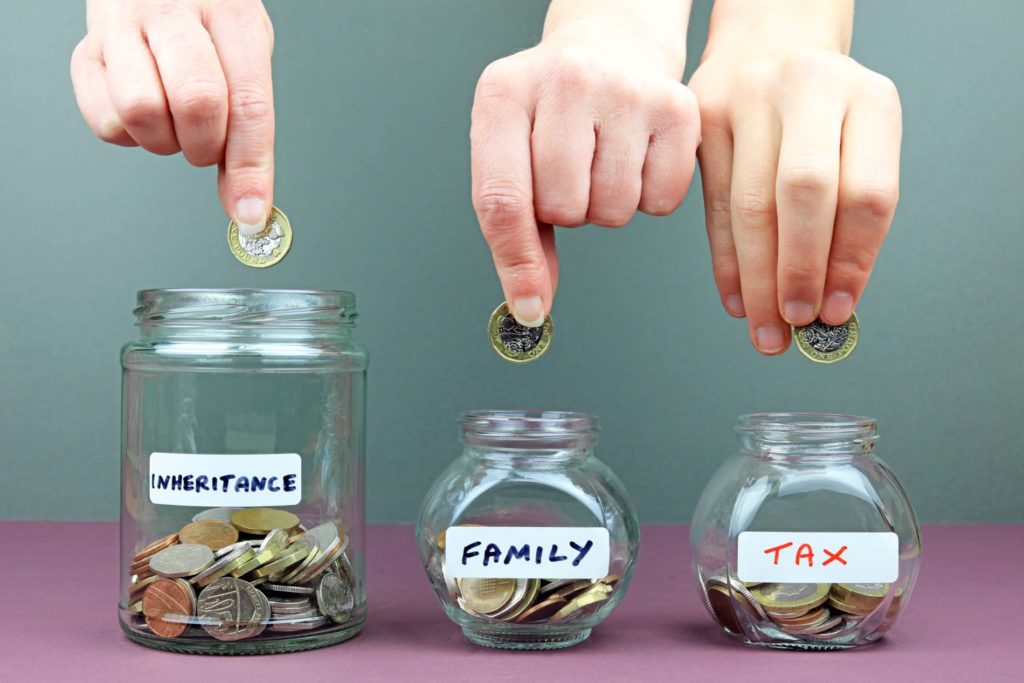
If your estate is not taxable, it may be a good idea to consider your options. In particular, take care when gifting to a child in your Will.
Your children may have amassed assets – property and pension pots – and the inheritance may push their estates over the thresholds available. One way of planning for the future could be to gift in your Will to the next generation, such as grandchildren, who may not have acquired such wealth at the time of your passing.
It is possible to gift to the next generation in one’s lifetime rather than on death in a Will. But this also needs to be considered carefully. A lifetime gift is a potentially exempt transfer (PET) and falls outside of your estate if you live for seven years after the gift is made. However, this is not always straightforward, as the gift may be subject to capital gains tax and property stamp duty land tax. Our property, commercial and corporate solicitors can advise and assist with enquiries.
It is anticipated that life insurance policies may in future be taken in the hope that they cover the IHT liability. Again, a good financial adviser can assist.
It is now more than ever, important to consider carefully making a Will. Careful planning may ensure that the generations to follow receive your assets without the unnecessary burden of IHT.
Planning for the future should also include consideration of the creation of powers of attorney.
The ability to choose your preferred attorneys – people you love and trust to make decisions for you when you need them to. This can be a little extra help when you feel unable to cope or merely lack confidence. It may be due to a lack of capacity and the power to make decisions for you in your best interests.
There are two types of power of attorney:
The Attorneys could be asked to assist but only with the consent of the person creating whilst capacity is intact.
Careful planning with the assistance of qualified professionals can safeguard your family’s future and minimise IHT burdens. Contact Davis Blank Furniss today for guidance on estate planning, making a Will, or setting up powers of attorney.
DBF are a class act. We used them for the sale of a house. Professional, clear and responsive. Craig and Belinda who handled our case were great. Nothing was too much trouble, responsive and easy to get hold of.
Dave Weston
“Very approachable, practical solutions to problems, but most of all very responsive which I personally think is very important because if you need help, you need it quickly, or at least to know someone is looking at it for you”.
Joanne Rowe, Finance Director, Greater Manchester Chamber
“Always able to contact, very approachable, friendly and professional”
Nives Feely, JAM Recruitment
“I believe I have been able to establish a professional working relationship with everyone I have come into contact. Importantly, I sense the relationships which have been established give me the confidence that I can make contact with Davis Blank Furniss at any time and on any matter. I would also like to express my thanks to the very impressive “gatekeepers” who work in reception, not only for making me very welcome, but also for their professionalism”
Bill Pryke, CEO, Chartered Institution of Civil Engineering Surveyors
“Thank you for your efficient and friendly help throughout this process. We have had it easy but your approach has been part of that”.
Robert Amsbury (Conveyancing Client)
“I would like to take this opportunity to thank you personally for the ongoing support and assistance the firm has offered to our parents over the years. I hope also that we may be able to call on you if necessary in the future.”
Valerie Fisher (Probate Client)
“Jo always provides great service, understands our needs and delivers on her promises. Our needs are relatively simple but the complexity arises out of the volume of work and short time frames, Jo always delivers.”
Peter Fernandez, Corporate Director at Royal Bank of Scotland
“A big thank you to all who dealt with my wife’s claim… We would not hesitate to recommend Davis Blank Furniss to anyone that may be in a situation like we have been…”
Anon (Personal Injury client)
“Before putting my case in Kirsty (Morbey)’s capable hands I’ve met a couple of other solicitors. None of them listen to me as intently as Kirsty and showed me as much empathy and understanding as she did. Simultaneously she was able to look at my case from legal perspective, explain all the options and follow each of our meetings with written summary of the discussed matters (in timely manner). Her advice was invaluable and led me to successfully ending the case matter (hopeful for good). I’m forever grateful for he work and would definitely recommend her to anyone looking for reliable, knowledgeable and committed solicitor”.
Anon (Family client)
Our Manchester office is rated 5 stars on Google
